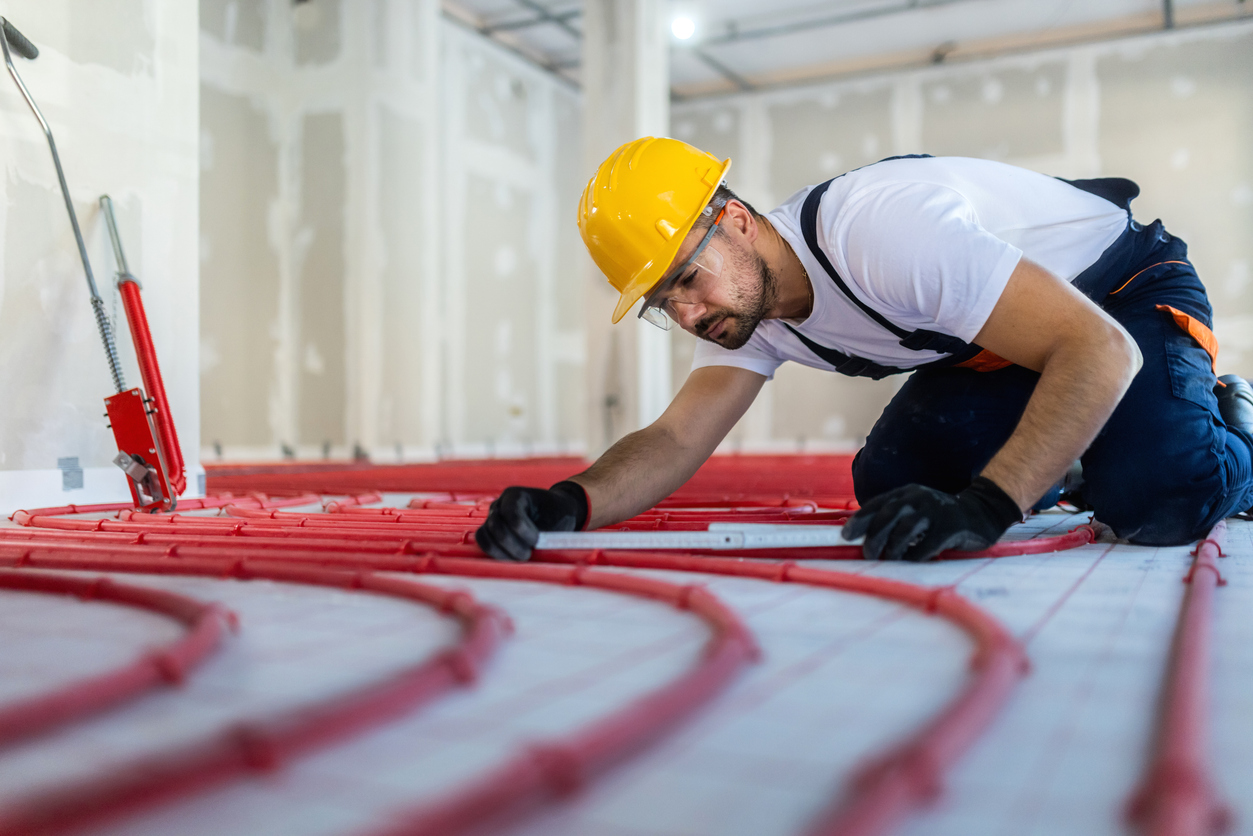
When a broker asks what general liability insurance covers on an active construction site, the answer points to third-party injuries and property damage arising from the contractor’s covered operations. A visitor could trip over job-site debris, a vendor could be injured while making a delivery, or a contractor could damage existing or neighboring property while work is underway. The timing is important: Claims arising during the job fall under ongoing operations, while losses that occur after the work is complete raise a different set of coverage questions.
What Does General Liability Insurance Cover During Construction?
Commercial general liability (GL) can respond when a contractor becomes legally liable for bodily injury or property damage to others arising from business operations.
Consider a remodeler who accidentally punctures a plumbing line while removing cabinetry. Water then damages finished flooring in an adjacent room. Or debris from a contractor’s work damages a neighboring building. Both scenarios involve property damage arising while operations are underway.
A GL policy may also cover legal defense costs when a liability claim falls within the policy’s coverage, subject to its terms and limits.
Damage caused by a contractor’s work does not mean every resulting expense falls under GL. What property was damaged, what work the contractor was performing, and which exclusions apply can all affect the claim. Brokers should review policy language carefully rather than assume any job-site property damage is covered. Common contractor GL mistakes can include overlooking exclusions or relying on certificates without confirming the underlying endorsements.
When Is a Claim Part of Ongoing Operations?
Ongoing operations refers to work or business activity that has not been completed or abandoned.
A plumbing leak that causes property damage while installation is still underway presents an ongoing-operations exposure. If the installation has been completed and damage first occurs later, the claim moves into completed-operations territory.
Note that additional insured status covering ongoing operations does not automatically extend to completed operations. If a construction contract requires protection during the project and after completion, brokers need to identify both requirements and confirm that the requested endorsements address them.
What Should Brokers Check for an Active Construction Project?
A strong submission provides the underwriter with enough information to understand what the contractor will be doing on-site.
- Operations mix: Break down the percentage of work involving remodeling, service and repair, new construction, or other activities.
- Subcontracted work: Identify how much work the insured performs directly versus subcontracting, which trades are subcontracted, and how subcontractors are selected.
- Project details: Describe the size and type of projects, along with the applicable exposure basis, such as payroll or gross sales.
- Contract requirements: Flag additional insured status, primary and noncontributory wording, waiver of subrogation, and completed-operations requirements before sending the account.
- Loss history: Include prior losses and relevant details that help explain how the contractor operates.
Specific information at submission gives the underwriter a clearer view of the active-site exposure and reduces follow-up for basic account details.
Match the GL Program to the Work Underway
General liability insurance for contractors starts with understanding what the contractor does, where the work takes place, and how responsibilities are divided among contractors and subcontractors. Brokers can then evaluate how the policy addresses liabilities that could arise while those operations are underway.
Have an eligible contractor account? Contact Commodore to obtain a premium indication.
About Commodore
Commodore Insurance Services, Inc. (Commodore) is a California corporation that operates as a Managing General Agency and Program Manager. Since incorporating in 1990, Commodore has developed an expertise in the production and underwriting of insurance products for businesses across the West Coast. Our focus is on providing top-level insurance products to our clients while striving to make it easy to do business for our brokers. Try us and find out why we have continued to be successful for more than 27 years and are recognized as the trusted leader in small business insurance.