Property damage to an existing home, an injured visitor at an active job site, or a problem that causes damage after the work is complete can all become general liability claims for a residential remodeler. For brokers placing contractor liability insurance, understanding how those claims develop can help clarify the contractor’s exposure before the account reaches underwriting.
Residential remodeling creates a particular challenge: The contractor works around property that is already finished, occupied, and valuable. A relatively modest project can still produce an expensive claim when something goes wrong.
Why Residential Remodeling Generates Liability Claims
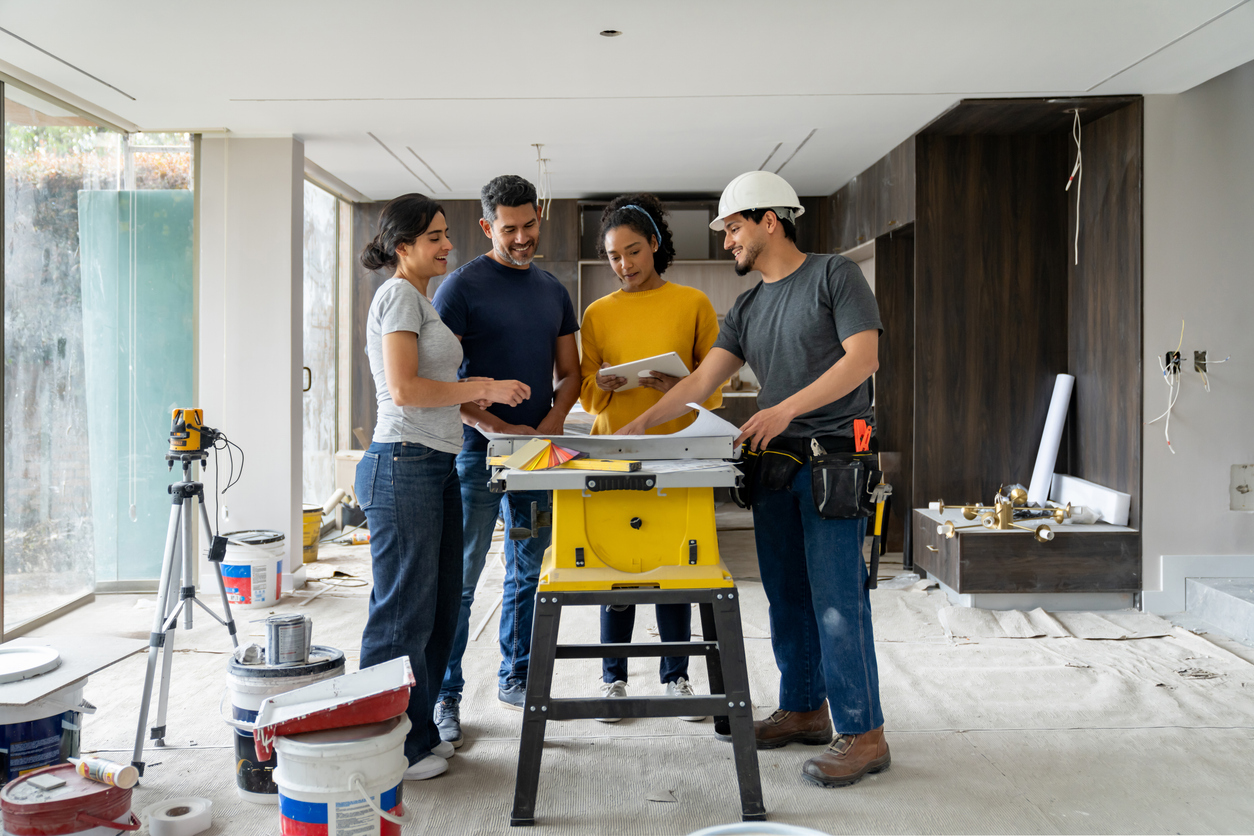
Remodelers often have to exercise particular caution in their work environments. A kitchen renovation may take place next to finished flooring and cabinetry. Bathroom work can involve existing plumbing and fixtures. Homeowners, delivery drivers, vendors, and other visitors may continue moving through or around the job site while work is underway.
Each project also represents a separate location where a third party could suffer bodily injury or existing property could be damaged. Project value alone does not tell the full story. A contractor performing a high volume of smaller jobs can still accumulate substantial exposure and frequent claims across locations.
General Liability Claims Brokers Should Expect
Several claim scenarios can arise from residential remodeling operations.
Damage to Existing Property
A contractor installing cabinets might damage finished flooring while moving materials through the home. Demolition work could damage an adjacent wall or fixture that was supposed to remain intact. General liability questions can become more complicated when a claim involves the contractor’s work itself versus resulting damage to other property, making the circumstances of the loss important.
Water Damage
Plumbing connections, fixture installation, and other remodeling work can create the potential for water damage to parts of the home outside the contractor’s immediate work area. The Insurance Information Institute gives a similar commercial general liability example: construction work that accidentally causes water damage to a customer’s home.
Third-Party Bodily Injury
Homeowners, guests, vendors, or delivery personnel can encounter debris, materials, cords, tools, or other conditions at an active remodeling site. As such, third-party slips, trips, falls, and injuries involving job-site conditions are among the liability exposures faced by remodelers and general contractors.
Damage to Neighboring Property
Remodeling work does not always stay within the boundaries of the immediate work area. Debris, materials, equipment, or contractor operations can damage neighboring homes, common areas, vehicles, or other third-party property.
Completed Operations Claims
Problems can surface after a remodeling job is finished. If the contractor’s completed work later causes bodily injury or property damage, the contractor could face allegations involving poor workmanship, failure to meet specifications or building codes, substandard materials, incorrect installation or repair, faulty equipment, or improper design.
What Underwriters Need To Understand About the Risk
Loss history provides one part of the underwriting picture. A strong submission also explains what the remodeler does and how the business operates. Be sure to address the following factors.
- Scope of work: A contractor focused on interior finish carpentry operates differently from a general remodeler coordinating multiple trades. Typical project size, annual job volume, and the types of residential properties involved can add important context.
- Subcontractor use: Brokers should identify how much work the contractor subcontracts, which trades perform that work, and what insurance and contractual requirements apply to subcontractors.
- Job-site practices: How does the contractor protect finished surfaces and areas outside the work zone? How are materials and debris managed when homeowners or other third parties remain on the premises? What controls are in place when work could affect neighboring property?
- Licensing, experience, years in business, and clear descriptions of current operations: Specific information gives the underwriter a clearer basis for evaluating the account and providing a timely premium indication.
Helping Brokers Place Better Remodeling Risks
A better contractor general liability insurance submission starts with understanding the work before sending the application. Brokers should know the contractor’s current operations, project mix, subcontractor use, typical job volume, and the third-party property and bodily injury exposures those jobs create.
Commodore Insurance Services specializes in general liability programs for contractors, including eligible remodeling and general contractor classes. Our programs also offer additional insured endorsements with completed operations for residential and commercial work, subject to program eligibility and policy terms.
Have a remodeling contractor account to place? Get in touch with us to discuss the risk and request a premium indication.
About Commodore
Commodore Insurance Services, Inc. (Commodore) is a California corporation that operates as a Managing General Agency and Program Manager. Since incorporating in 1990, Commodore has developed an expertise in the production and underwriting of insurance products for businesses across the West Coast. Our focus is on providing top-level insurance products to our clients while striving to make it easy to do business for our brokers. Try us and find out why we have continued to be successful for more than 27 years and are recognized as the trusted leader in small business insurance.