Two businesses may both fall under the artisan contractor label while presenting different third-party liability exposures. An interior carpenter may work inches from finished flooring, cabinetry, and countertops, while a concrete contractor may work around driveways, walkways, landscaping, and neighboring property. For brokers, evaluating artisan contractors insurance starts with understanding the work itself rather than relying on a broad contractor category.
How Does the Trade Change the Third-Party Claim Exposure?
Each trade creates its own opportunities for a contractor’s work to injure someone or damage property belonging to someone else.
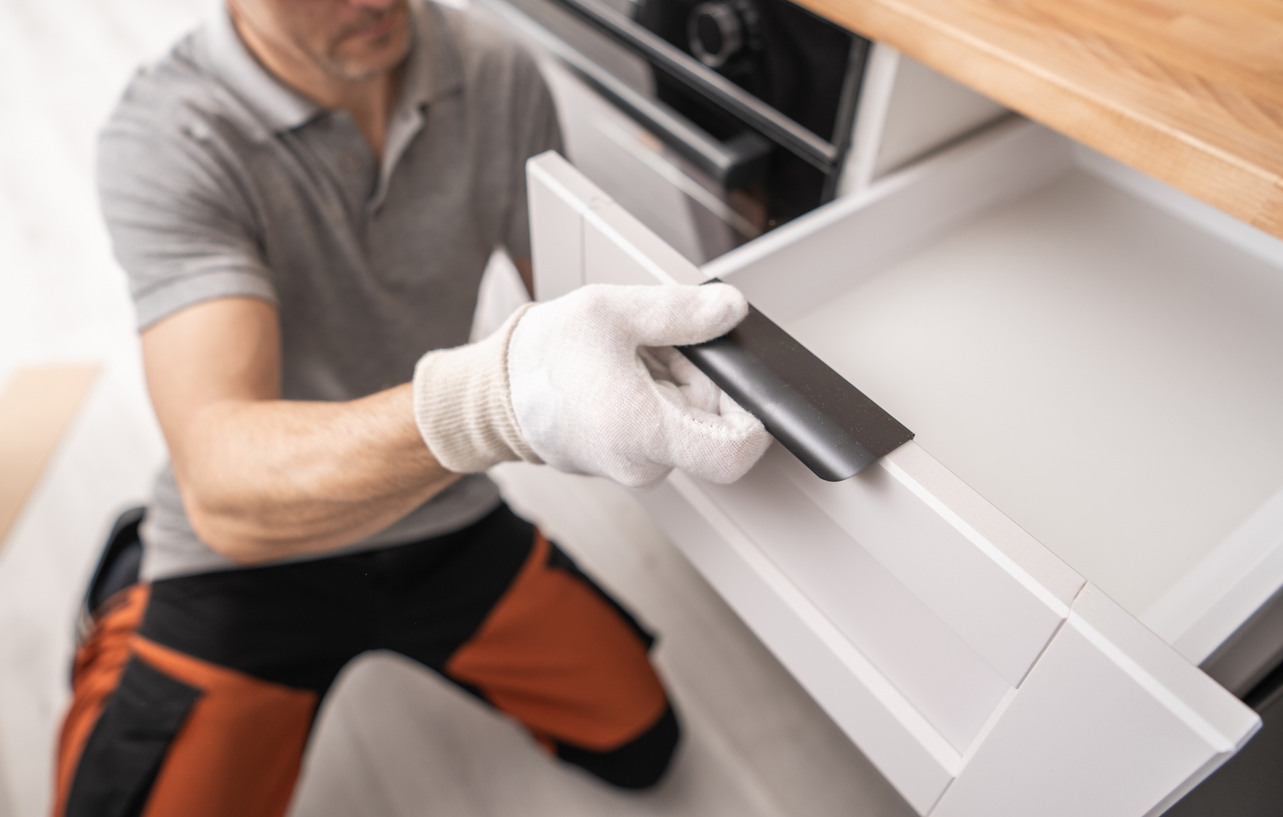
An interior carpenter installing cabinets could damage an existing countertop or finished floor. A plumber repairing a supply line could cause water damage to surrounding property. A concrete contractor working near an existing structure could damage adjoining surfaces or property while preparing or pouring the job.
General liability can respond to covered claims involving third-party bodily injury or property damage arising from business operations, subject to the policy’s terms, exclusions, and limits.
The examples share one feature: The contractor performs work around property the contractor does not own or third parties. The specific trade, task, tools, materials, and surroundings determine what could be affected if something goes wrong.
Where Is the Contractor Doing the Work?
Location can change the exposure even when the contractor performs the same type of work.
A contractor working inside an occupied home may be around residents, furniture, flooring, and finished surfaces. Work inside a commercial building can add customers, tenants, merchandise, or equipment to the area. On an active construction site, other contractors, visitors, building materials, and project property may all be nearby.
Bodily injury exposure can develop just as quickly. A customer or visitor could trip over tools or materials left in a work area, for example.
Job size does not tell the whole story, either. As Commodore has discussed in our look at general liability risks in small repair work, even limited work can place a contractor around customers and property that could become part of a liability claim.
What Should Brokers Ask About the Operation?
A useful artisan contractor insurance submission should describe how the contractor works, not simply provide a business name or trade description. Brokers can start with a few specific questions.
- Work performed: Does the contractor handle installation, repair, remodeling, new construction, or a combination?
- Work location: Does the insured work in occupied homes, commercial premises, or active construction sites?
- Direct operations: Which tasks do the insured and its employees perform themselves?
- Subcontracting: What percentage of the work goes to subcontractors, and which trades do they perform?
- Classification: Does the classification accurately reflect the operations described on the application?
Clear answers help the underwriter understand which people and property may be exposed while the contractor performs the work.
Describe the Work Before Describing the Risk
A precise description of operations gives brokers and underwriters a stronger starting point for evaluating an artisan contractor account. The trade matters, but so do the individual tasks, work locations, surrounding property, and use of subcontractors.
For an eligible small artisan contractor, contact Commodore to obtain a premium indication.
About Commodore
Commodore Insurance Services, Inc. (Commodore) is a California corporation that operates as a Managing General Agency and Program Manager. Since incorporating in 1990, Commodore has developed an expertise in the production and underwriting of insurance products for businesses across the West Coast. Our focus is on providing top-level insurance products to our clients while striving to make it easy to do business for our brokers. Try us and find out why we have continued to be successful for more than 27 years and are recognized as the trusted leader in small business insurance.